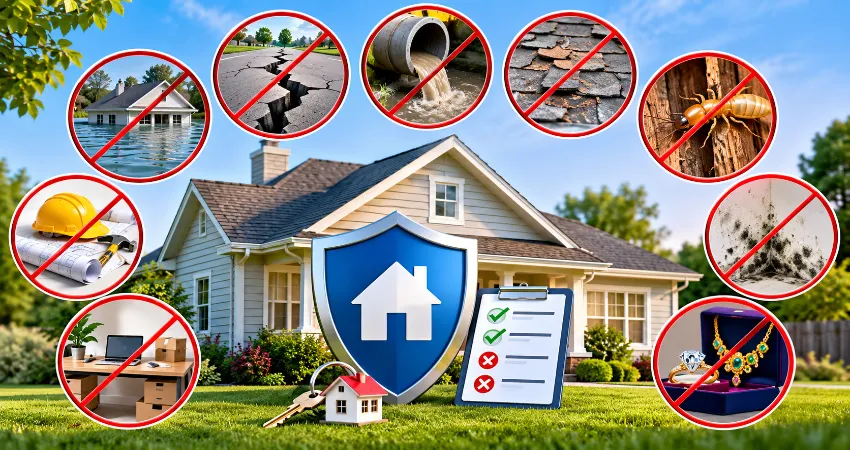
Homeowners insurance provides important financial protection against unexpected property damage, theft, and certain liability claims. However, many American homeowners assume their policies cover virtually every disaster or expensive repair. In reality, standard home insurance includes exclusions, coverage restrictions, and payment limits that can leave property owners responsible for substantial expenses.
Understanding what home insurance does not cover is particularly important when purchasing a house, renewing a policy, or preparing for natural disasters. For example, damage from a burst water pipe might qualify for coverage, while flooding from an overflowing river generally requires separate insurance. The difference depends on how the damage occurred and the terms of the policy.
This guide explains ten common homeowners insurance exclusions in the United States, why they matter, and practical steps to reduce coverage gaps. Policies differ by insurer, state, and coverage form, so homeowners should always review their actual insurance documents before making financial decisions.
1. Flood Damage
Flood damage is one of the most significant exclusions in standard homeowners insurance. Water entering a home because of overflowing rivers, coastal storm surge, or widespread surface flooding generally is not covered. This distinction matters because regular homeowners coverage may protect against certain sudden indoor plumbing failures but not rising water from outside.
Homeowners can explore separate flood policies through FEMA’s National Flood Insurance Program (NFIP) or private insurers. According to the National Association of Insurance Commissioners (NAIC), flood exposure exists even outside designated high-risk areas. NFIP policies generally have a 30-day waiting period, although exceptions apply. Reviewing local flood maps and purchasing coverage before a storm approaches are sensible precautions.
2. Earthquakes and Earth Movement
Standard home insurance generally excludes damage directly caused by earthquakes and other forms of earth movement. Cracked foundations, collapsed walls, and structural displacement resulting from an earthquake can create major repair expenses.
Homeowners in California, Alaska, Washington, and other earthquake-prone regions should investigate dedicated earthquake coverage. It may be available through a separate policy or endorsement. Earthquake deductibles can differ considerably from regular homeowners deductibles and may be calculated as a percentage of the insured dwelling amount. Coverage for sinkholes and other ground movement varies by state, making local policy terms especially important.
3. Sewer Backups and Drain Overflows
A sewage backup can damage flooring, furniture, electrical systems, and stored belongings. Yet standard homeowners policies commonly exclude water entering through backed-up sewers, drains, or sump systems.
For example, if a municipal sewer line becomes obstructed and wastewater enters a basement, the resulting damage might not qualify under ordinary homeowners coverage. Water backup endorsements can help address this exposure. However, coverage limits, exclusions, and definitions differ. Homeowners should also inspect sump pumps, maintain drainage systems, and ask whether the endorsement covers sump pump failure.
4. Normal Wear and Tear or Poor Maintenance
Home insurance is primarily designed for covered unexpected losses rather than routine property upkeep. Aging roofs, deteriorating plumbing, worn flooring, and equipment that gradually stops functioning generally are maintenance responsibilities.
Consider a roof that slowly develops leaks because damaged shingles were never repaired. An insurer may deny damage attributable to gradual deterioration. By comparison, sudden roof damage from a covered windstorm may qualify, subject to the policy’s conditions and deductibles.
Regular inspections, prompt repairs, and dated maintenance records help homeowners protect their properties and document their condition.
5. Termite, Rodent, and Other Pest Damage
Damage caused by termites, rodents, and other infestations is typically excluded from standard homeowners insurance. Insurers generally consider pest prevention and treatment part of maintaining a property rather than an unexpected insured event.
For instance, termites that gradually weaken wooden support beams can create expensive structural problems without triggering a covered claim. Similarly, rodents chewing electrical wiring may leave homeowners responsible for repairs.
Professional pest inspections, moisture control, sealed entry points, and timely treatment can reduce these risks. Before purchasing an older property, buyers should consider obtaining a specialized pest inspection.
6. Mold and Long-Term Moisture Damage
Mold can develop after prolonged moisture exposure, leaking pipes, or inadequate ventilation. Standard homeowners policies often exclude mold caused by ongoing leaks, humidity, or neglected maintenance.
However, mold-related coverage is not always completely unavailable. Some policies provide limited protection when mold directly results from a covered sudden event, such as an unexpected pipe burst. Special restrictions or dollar limits may still apply.
Homeowners should investigate leaks quickly, dry affected areas, maintain ventilation, and document water damage. Asking the insurer about mold remediation limits is particularly useful for homes with basements or recurring moisture problems.
7. Expensive Jewelry, Artwork, and Collectibles Beyond Policy Limits
Homeowners insurance commonly includes personal property protection, but expensive belongings can have special reimbursement limits. Jewelry, fine art, antiques, collectibles, and certain other valuable items may not receive their full replacement value under ordinary coverage.
For example, a stolen necklace valued at $8,000 may exceed the applicable jewelry theft limit. Even though theft itself is a covered event, the reimbursement could be considerably lower than the necklace’s value.
Scheduled personal property coverage or other specialized endorsements may offer broader protection. Homeowners should maintain photographs, purchase receipts, and appropriate appraisals. It is also important to distinguish theft-specific limits from the limits applicable to other causes of loss.
8. Home-Based Business Equipment and Liability
Operating a business from home does not automatically mean business-related property and activities receive full protection under a homeowners policy. Business inventory, specialized equipment, and certain liability claims may be excluded or covered only up to small limits.
For instance, a homeowner running an online retail business may discover that damaged merchandise stored in a spare bedroom is not fully insured. Likewise, an injury involving a visiting business customer may raise liability coverage questions.
Business owners should disclose their activities to their insurer and consider a home-business endorsement, specialized business property policy, or appropriate commercial insurance.
9. Building Code Upgrades After a Covered Loss
Rebuilding a damaged home can involve additional expenses when local building codes have changed since the property was constructed. Standard policies may exclude or limit the extra costs required to comply with newer regulations.
Imagine an older house suffering substantial fire damage. Although the fire itself is covered, local authorities might require updated electrical systems or structural improvements during reconstruction. Those upgrades could cost more than repairing the original damage.
Ordinance or law coverage can help pay certain additional compliance expenses. Homeowners with older properties should review whether their policy includes this protection and whether its limit is sufficient.
10. Intentional Damage and Deliberate Property Destruction
Home insurance generally does not cover losses intentionally caused by an insured person when the policy’s intentional-loss exclusion applies. Insurance is intended to protect against qualifying unforeseen events, not deliberate destruction.
For example, intentionally damaging insured property and then submitting a claim as though the damage were accidental may result in denial and serious legal consequences. However, vandalism committed by an unrelated third party is often treated differently and may be covered, depending on the circumstances.
Homeowners should understand the difference between accidental damage, excluded intentional conduct, and covered vandalism. Policy definitions and applicable state laws can influence the outcome.
How to Identify and Reduce Home Insurance Coverage Gaps?
The most effective way to identify missing protection is to review the declarations page, exclusions, endorsements, deductibles, and coverage limits together. The declarations page shows important coverage amounts, but it does not explain every restriction.
Start by matching coverage to realistic household risks. A coastal property may need particular attention to flood and wind-related provisions, while an older home may benefit from evaluating building code upgrade coverage. Homeowners with expensive belongings should examine special personal property limits rather than relying only on the total contents coverage amount.
Compare additional coverage costs with the expenses you could reasonably absorb yourself. Request written explanations for unclear provisions, update your home inventory annually, and reassess coverage after renovations or major purchases. Remember that an excluded cause of loss, a deductible, and a coverage limit are three different reasons an insurer might pay less than the full repair cost.
Frequently Asked Questions
1. Does homeowners insurance cover every natural disaster?
No. Standard policies commonly cover certain events such as fire, lightning, and windstorms, but flood and earthquake damage are generally excluded. Coverage for other disasters depends on the location, insurer, policy wording, and applicable endorsements. Review each major hazard individually rather than assuming all natural disasters are included.
2. Is flood insurance required for every US homeowner?
No. Flood insurance requirements depend partly on property location and mortgage conditions. Certain properties in high-risk flood areas with federally regulated or insured mortgages must carry flood insurance. Other homeowners may purchase it voluntarily, including those living outside mapped high-risk areas.
3. Will home insurance pay for a leaking roof?
It depends on the cause. Sudden damage from a covered storm may qualify, while leaks resulting from deterioration, neglect, or long-term maintenance problems generally do not. The insurer may examine photographs, inspection reports, and the roof’s condition before deciding whether coverage applies.
4. Does homeowners insurance cover plumbing repairs?
A policy may cover resulting water damage from a sudden, accidental pipe failure, but replacing the deteriorated pipe itself may remain the homeowner’s responsibility. Gradual leaks and maintenance-related problems are commonly excluded. Coverage also depends on whether the water originated inside the plumbing system or from an excluded source.
5. Can homeowners add earthquake protection?
Yes. Earthquake insurance is available through separate policies or endorsements from participating insurers. Buyers should compare structural coverage, personal property limits, temporary housing provisions, and deductibles. Earthquake protection should be evaluated separately from ordinary homeowners coverage because its cost-sharing arrangements can be different.
6. Are expensive electronics fully covered?
Not necessarily. Electronics may fall under personal property coverage, but payment depends on the covered cause of loss, policy limits, valuation method, and any applicable exclusions. Devices used primarily for business may face additional restrictions. Maintain purchase records and review coverage after acquiring expensive equipment.
7. Does home insurance cover mold removal?
Sometimes, but coverage is often restricted. Mold resulting from long-term moisture, poor maintenance, or humidity is frequently excluded. Limited remediation coverage may apply when mold follows a covered sudden water event. The policy’s cause-of-loss requirements and specific mold limitations determine the available protection.
8. Will insurance cover damage to a vacant house?
Coverage can become more restricted when a property remains vacant for a period specified in the policy. Certain losses, including vandalism or water-related damage, may be excluded under vacancy provisions. Owners planning extended absences should notify their insurer and ask about appropriate vacant-property protection.
9. What happens when a home insurance claim exceeds coverage limits?
The insurer generally pays eligible losses only up to the applicable policy limit, after considering deductibles and other conditions. Remaining expenses are the policyholder’s responsibility. Homeowners can reduce this exposure by reviewing rebuilding estimates, updating dwelling limits, and examining additional coverage options before a loss occurs.
10. How often should homeowners review their insurance policies?
An annual review is a useful starting point, with additional reviews after renovations, major purchases, business changes, or significant changes in local hazards. Verify replacement costs, personal property values, deductibles, and exclusions. A licensed insurance professional can explain available options and help identify important coverage gaps.
Conclusion
Understanding what home insurance will not cover helps US homeowners avoid unexpected financial burdens. Floods, earthquakes, maintenance problems, pest damage, and other common exclusions deserve particular attention.
By reading policy terms carefully, maintaining the property, documenting belongings, and considering appropriate additional protection, homeowners can make more informed decisions about their insurance needs.
Disclaimer: This article provides general educational information about US homeowners insurance. Actual coverage depends on policy language, state law, endorsements, exclusions, and individual claim circumstances. Consult a licensed insurance professional for guidance specific to your property.
Leave a Reply